As the midterm election season unfolds, investors are keeping a close eye on the outcome due to the implications for Congressional control. Current forecasts suggest that a divided government is the most likely scenario, since Republicans hold slim majorities in both the House and Senate.1 Although a shift in party control would represent a change from the past two years, these situations are common and tend to occur during midterm election cycles.
While election outcomes are never certain, one thing that is clear is that the federal budget deficit grew to just under $2 trillion over the past year, its highest level in absolute terms since 2021.2 This means that the government spent significantly more than it received in revenues. This is likely to remain the case regardless of which party controls Congress next year since challenges such as rising interest costs and entitlement spending have built up over decades. This adds to the national debt, which has risen past $40 trillion, or over 120% of the size of the economy.3
For investors who follow these headlines, it can be natural to feel concerned, regardless of political views. This is why it’s important to maintain a long-term perspective that separates political issues from investment and financial planning ones. What do investors need to know about the deficit and election this political season?
The federal budget deficit has grown
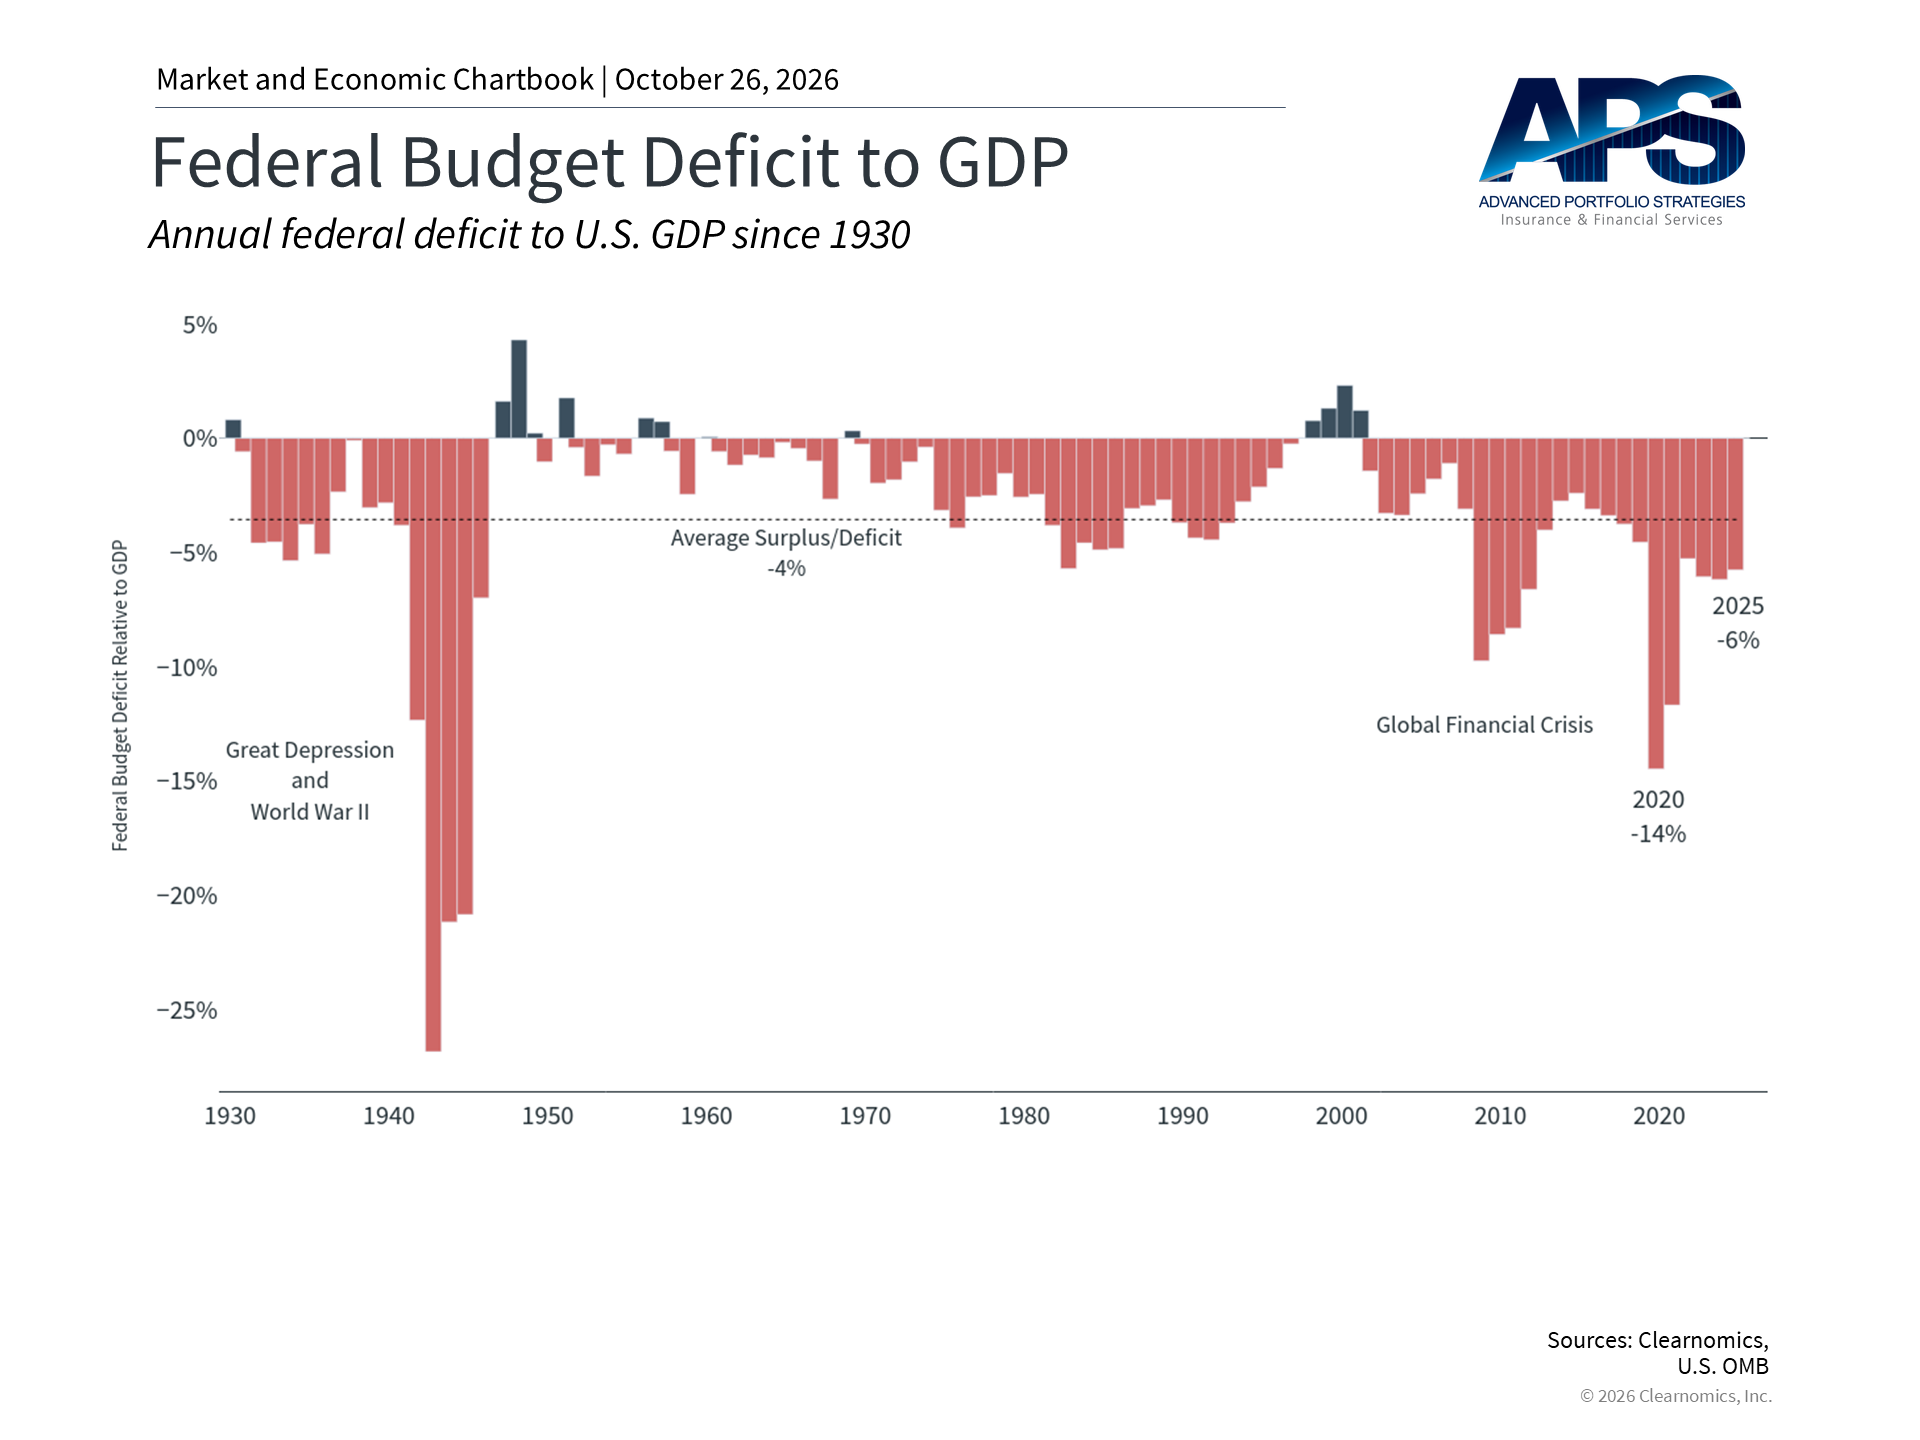 |
Before discussing the impact of government spending on financial markets, let’s first review the numbers. The federal government recorded a $1.99 trillion deficit for the fiscal year that ended September 30, 2026, which represents an increase of 12% from $1.78 trillion the prior year.4 This is because the government spent $7.4 trillion but only collected $5.4 trillion in revenue via taxes, tariffs, and other means.5
This difference is made up for with borrowing through the issuance of Treasury securities, which are bought by investors and institutions around the world. Based on current Gross Domestic Product (GDP) figures, the latest deficit is likely to be around 6% of GDP, similar to the ratio in 2025.6
The chart above shows that deficits in recent years have been high relative to history. The budget deficit has averaged 4% of GDP for nearly a century, and periods of financial and global disruption have led to wider gaps, such as during World War II and the 2008 global financial crisis.
Deficits tend to normalize after these events, but there are very few periods when the government has operated with a surplus. The last time the budget was balanced was during the Clinton administration after a strong decade of economic growth, and before that during the Johnson and Eisenhower administrations in the late 1960s and mid-1950s, respectively.
Over time, these annual deficits add to the total national debt, which surpassed $40 trillion for the first time in August. According to the Congressional Joint Economic Committee, this represents around $117,707 per American, or $298,606 per household.7
While these figures are all large and represent real fiscal challenges, it’s difficult to know how to interpret them. The reality is that adjusting portfolios based on these issues would historically have worked against financial goals. This is because deficits are the largest during times of economic and financial distress, which tend to be when markets are near their lows. Counterintuitively, these would have been the best times to invest.
Budget deadlines, the debt ceiling, and rising interest rates could be in the news
 |
That said, there are two implications that long-term investors should be aware of. First, the national debt is approaching the statutory debt ceiling of $41.1 trillion set by the One Big Beautiful Bill Act last year, which could be reached by mid-2027.8 The federal government’s deadline for a new budget is December 11, not long after the midterm election. Raising the debt ceiling will likely be one of the key debates for the next Congress and, if a decision is not made in time, there could be a government shutdown.
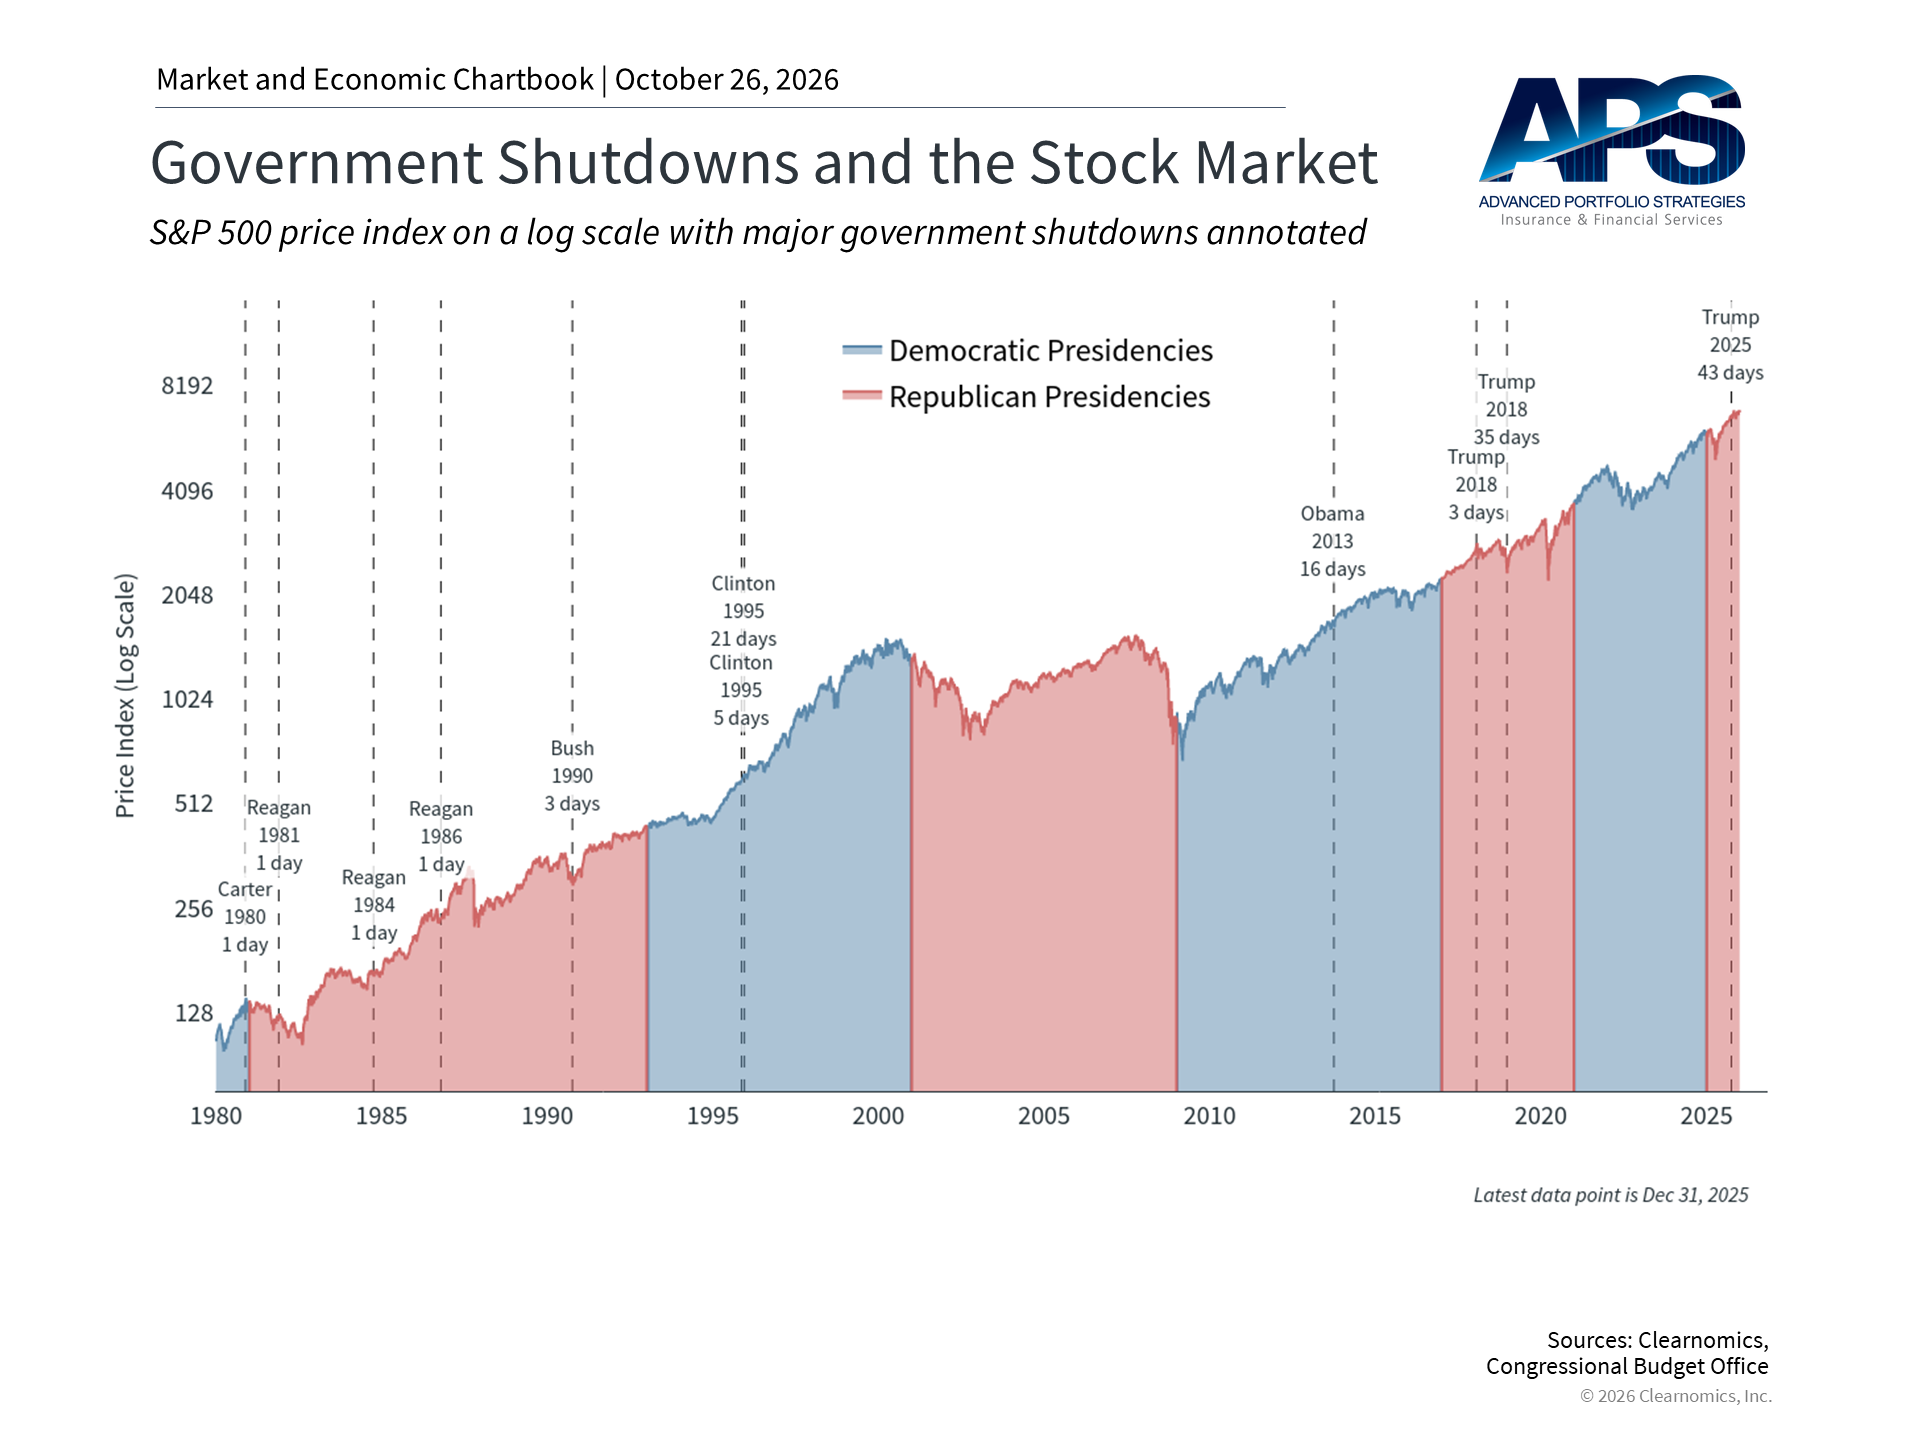
While shutdowns can result in hardship for federal workers and cause short-term market swings, major indices have tended to stabilize and look past these issues quickly. This is the case even during historically long shutdowns such as in 2018 and more recently in 2025. The chart above highlights historical government shutdowns and the steady rise in the stock market over this period. Of course, the past is no guarantee of the future, but this does highlight the importance of not overreacting to political news when it comes to investing.
Second, rising interest rates are compounding the government’s fiscal challenges. The 30-year Treasury yield has remained above 5% since June, while the 10-year yield is still hovering near this level. This matters because as existing government debt matures, it must be refinanced at higher rates, which increases interest payments and worsens the budget imbalance. This is one reason the Treasury Department has intervened by buying more Treasury securities to help stabilize U.S. interest rates.9 It has even engaged in other operations, such as supporting the Japanese yen, to indirectly stabilize rates.
Policy uncertainty can lead to short-term volatility
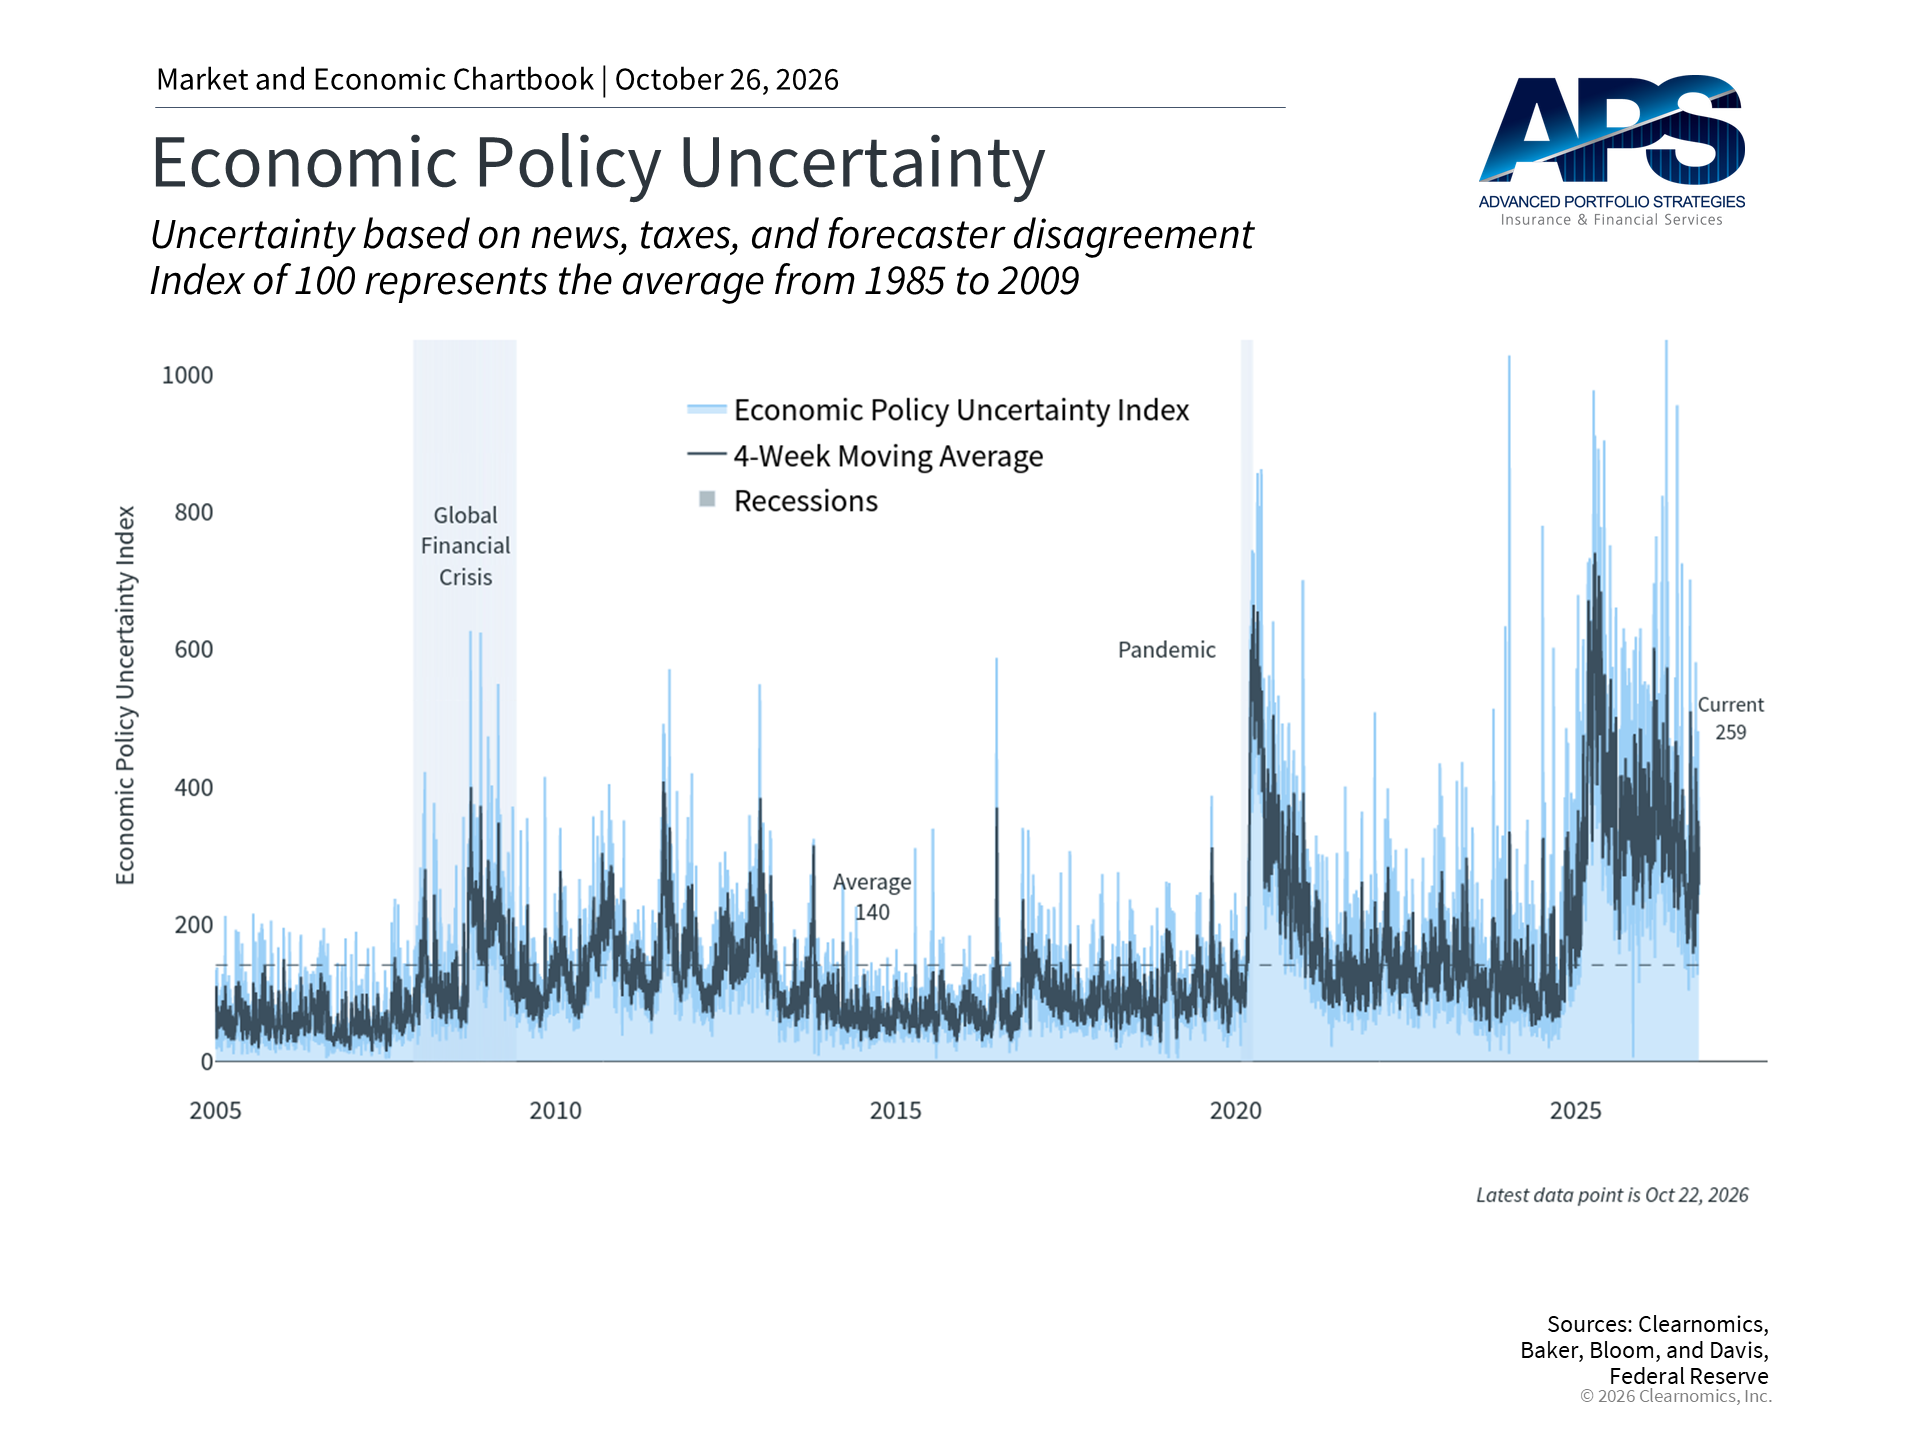 |
The national debt is a long-term challenge to which there are no simple solutions since it involves decisions around taxes, entitlement programs, and spending priorities. At the same time, predictions when it comes to policies have not always been accurate, especially during periods of strong economic growth. For example, the market decline that followed last year's tariff announcements was shorter than many expected, and gave way to a rebound that brought major indices to new all-time highs.
This is why it’s important as an investor to stay level-headed when it comes to political topics. The chart above shows that economic policy uncertainty has been a contributor to short-term market swings in recent years, but these periods have tended to be short-lived. Prior episodes, including this year’s geopolitical conflict in the Middle East, created volatility as investors tried to measure the impact on the economy and corporate profits. While oil prices are still elevated, markets have performed well due to healthy economic trends.
None of this is to say that every year is positive, the national debt is not a challenge, or that policy is irrelevant. Instead, the point is that underlying factors such as corporate earnings, interest rates, and longer-term economic trends tend to be the primary drivers of market performance over time. For investors, it’s more important to make sound investment decisions based on these longer-term trends, rather than on political headlines or which party controls Congress.
The bottom line? The midterm election and the growing federal deficit are important topics, but history shows that long-term portfolio outcomes are driven by fundamentals rather than by political outcomes.
References
1. https://www.realclearpolling.com/latest-polls
2. https://fiscaldata.treasury.gov/americas-finance-guide/national-deficit/
3. https://fiscaldata.treasury.gov/americas-finance-guide/national-debt/
4. https://fiscaldata.treasury.gov/americas-finance-guide/national-debt/
5. https://www.realclearpolling.com/latest-polls
6. Clearnomics research using U.S. Treasury and Bureau of Economic Analysis data, as of October 23, 2026
7. https://www.jec.senate.gov/public/index.cfm/republicans/debt-dashboard
8. Clearnomics research and U.S. Treasury data, as of October 23, 2026
9. https://home.treasury.gov/news/press-releases/sb0607
Index Descriptions
S&P 500
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
APS Management Group, Inc. is a registered investment adviser. Information presented is for educational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any specific securities, investments, or investment strategies. Investments involve risk and, unless otherwise stated, are not guaranteed. Be sure to first consult with a qualified financial adviser and/or tax professional before implementing any strategy discussed herein. Past performance is not indicative of future performance.
APS Management Group, Inc. does not provide tax or legal advice; consult your tax or legal professional regarding your particular situation.
Opinions, estimates, forecasts, and statements of financial market trends that are based on current market conditions constitute our judgment and are subject to change without notice. We believe the information contained in this commentary has been obtained from sources that are reliable. This publication is for informational purposes only and is not intended as an offer or solicitation with respect to the purchase or sale of any security.
Copyright (c) 2026 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company's stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security--including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.